THE SHORT ANSWER
To search a Mississippi car for a lien, type its VIN into the preview. You get any lien, theft or impound entries filed under that number. A lender's name means a loan may be open. No result proves nothing, so get the lender's name and a payoff letter showing an end date from the seller, and insist on a written release before the final payment.
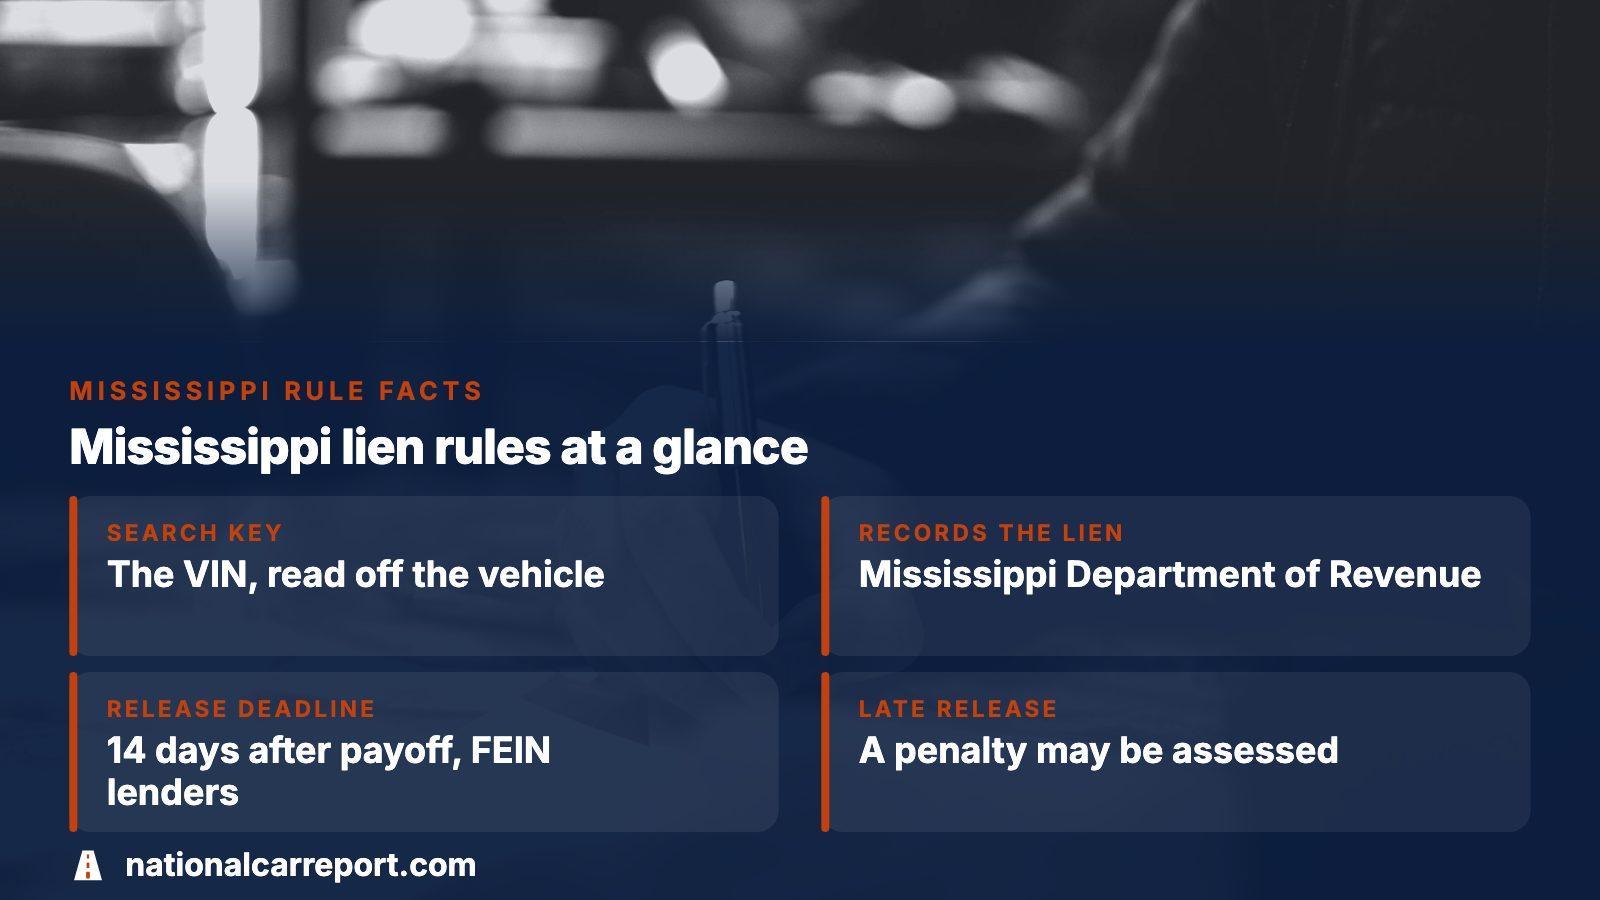
- Search key
- The VIN, read off the vehicle
- Who records the lien
- The Mississippi Department of Revenue, on the title
- Lender release deadline
- 14 days after payoff, for lenders with a FEIN
- Penalty for a late release
- $250 per incident may be assessed
What the preview looks for on a Mississippi car
A seller can be sincere and still be wrong about who else has a claim on the car. A bank may have financed it two owners back, a yard may have towed it last winter, or police may have listed it as stolen. All of that hangs on the VIN. NationalCarReport's preview reads the number and reports what it found before you commit to the full report.
- Lien records: a lender's claim, if it reached a source the search reads
- Impound records: whether a yard held the car and whether it was sold off
- Theft records: a stolen listing and whether the car was recovered
- Salvage or flood brands on the title, which pull down the car's value
The search tells you where to look. Only the party owed can say the debt is gone.
How Mississippi records a lender on a title
Mississippi has been moving its lien paperwork away from paper. The Department of Revenue runs an electronic lien program in which lenders enroll through approved service providers, and a title that carries an electronic lien is issued the next business day. Lenders with a federal employer number must clear their claim electronically once the loan is paid, and that is the rule that matters most when you are the one buying.
A secondary lien can also sit in the system, though only the primary lender can start electronic transactions. Individuals who lend money on a car are not allowed into the electronic process under the law, so a private loan on a car follows different paperwork.
Read the title before you read anything else
A lender's name on the title means the seller does not hold the whole claim. Ask for that lender's name, phone number and a current payoff figure, then confirm all three with the lender directly.
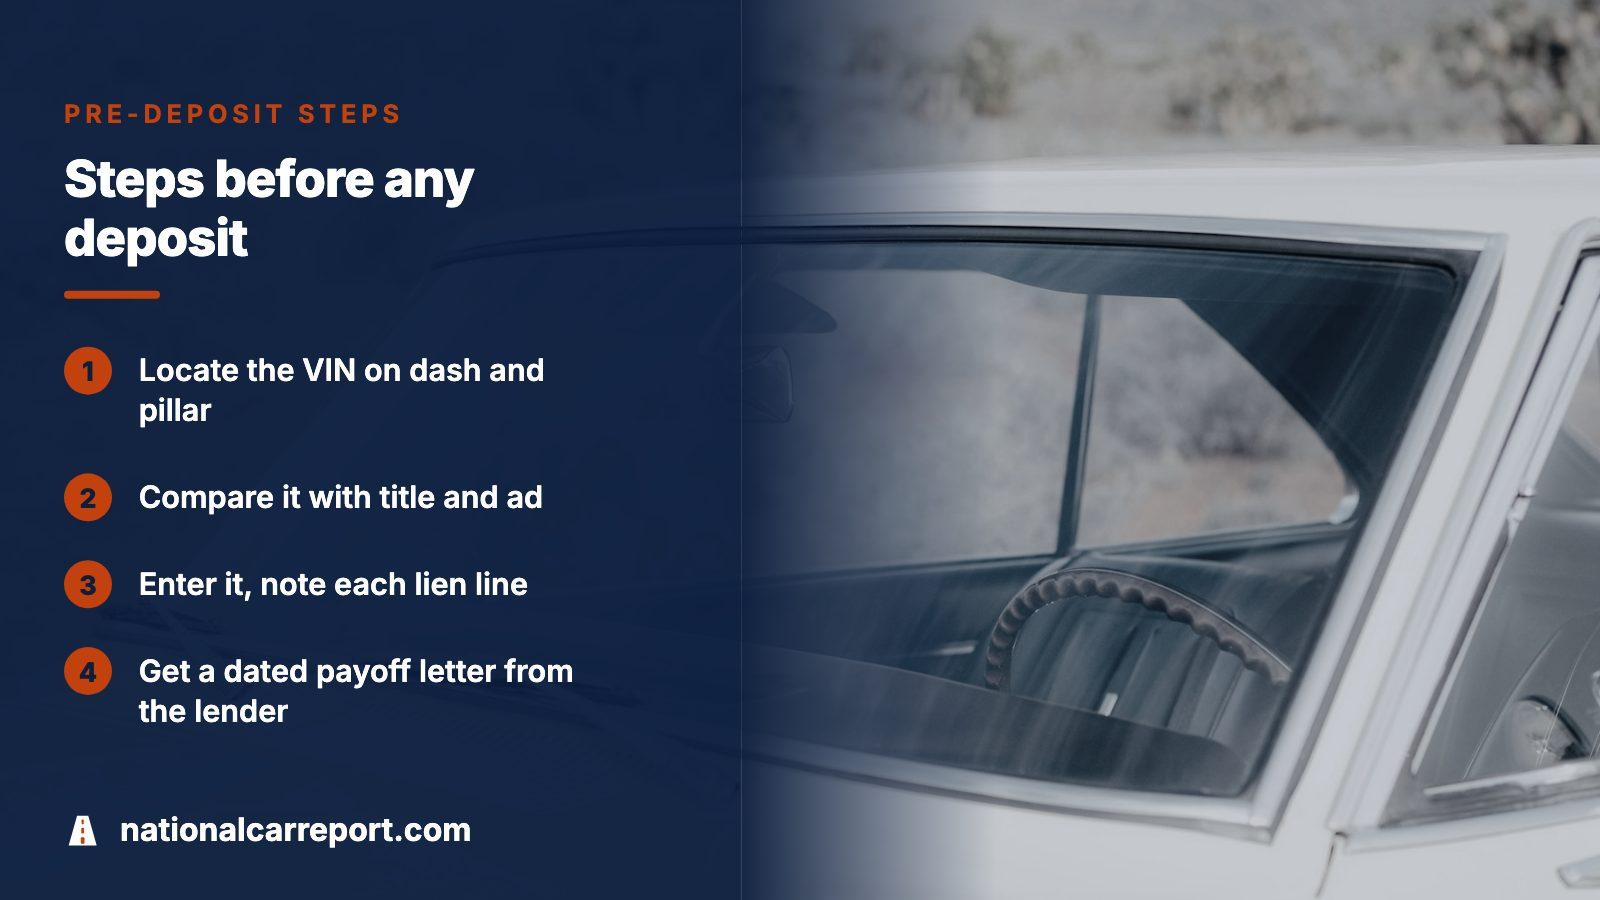
Five steps to take before any deposit changes hands
- Locate the VIN on the dashboard plate and on the door pillar; the 17 characters should match.
- Compare it with the title, the sale paperwork and the ad.
- Enter it in the preview and write down each lien, theft or impound line.
- When a lender appears, have the seller name it and produce a payoff letter with an expiry date.
- Weigh the open questions against the cost of the full report, a single payment with no subscription.
Do this at home, not in the seller's driveway with cash in hand.
What the state's own tools do and do not tell a buyer
Mississippi's revenue department offers a status link for title applications and a record inquiry account that searches by VIN, title number or tag number. Its pages never say the public can use either to see a lien on someone else's car, and the portal would not display for us, so we cannot say what a search there returns. For a state answer, call the motor vehicle services office.
Personal details are separate. Federal law, the Driver's Privacy Protection Act, shields names, addresses and licence numbers held in motor vehicle records, so the department hands them only to applicants with a qualifying exemption on its records request form. A VIN lien search is not an owner lookup.
Why a national title report will not settle the lien question
The federal title system, NMVTIS, is useful, but check its scope. The Justice Department describes its content as current title data and brands, the latest odometer figure, an insurer's salvage or total-loss ruling, and moves to junk or salvage yards. Liens are not on that list, and its reports are short by design.
| Question | Where the answer lives |
|---|---|
| Does a lender hold a claim? | The title record and the lender itself |
| Was the car branded salvage or flood? | State title brand, national title data |
| Is the odometer reading consistent? | National title data, inspection |
| Was the car stolen or towed? | Theft and impound records tied to the VIN |
Reading a hit, a blank, and the red flags
A hit with a lender's name is a prompt for questions, not a verdict, since loans get paid off and records lag. A blank is no clean bill either; lender claims are not collected in one national file.
- The seller cannot say who financed the car, or the name changes between calls
- No title in hand, with a story about a lender who is slow to mail it
- A payoff letter with no date, no lender contact or an out-of-date amount
- A seller who wants cash today and will not wait for the lender to confirm
- A title that is blank where the buyer's name should go
The revenue department says never to accept a title with the buyer line left empty, and calls that a violation of state law. Walk away.
When the loan is paid off: what a release should look like
After payoff, a lender has 14 days to clear the claim online, and a late release can draw a $250 penalty. That helps you: if a seller says the loan is cleared but the lien lingers, you can point to the deadline. Some lenders instead sign off on the paper title's front and hand it over, then notify the state, which prints no new title.
If a lender's name was left off a title in error, the department reviews the paperwork and a corrected title follows in 24 to 48 hours once confirmed. Have the seller settle that before the sale. When buying outright, pay the lender directly, get the release in writing, then transfer the title.
Old liens are removed on a schedule
Mississippi asks lenders to recertify any unsatisfied lien older than 8 years by December 1 each year. Liens not recertified come off the state system the following January, so an old claim can vanish from the record without the debt being settled.
If the title is missing or still with a lender
A missing title is a stop sign. The state wants a replacement title in hand before a sale moves forward, applied for on Form 78-006 at $9.00 by mail. If no title can be had at all, the route is a title bond: a surety bond set at 1.5 times the car's average trade-in value, plus an affidavit of ownership and a bill of sale.
Cars from other states raise the same issue. When a lender or the other state holds the title, the department holds your application until it arrives, and without it nothing is processed. Remember that when a seller says the title is in the mail.
Cost, and the sensible order of steps
Seeing the preview costs nothing. When it raises a question, the full report is one payment per VIN, and you can buy 3, 5 or 10 together if several cars are on your list. No subscription. The pricing page lists the current amounts.
Start with the preview, call the lender it names, then make your call. If the lender confirms the balance and will release on payment, you have a path. If nobody gives a straight answer, pass, whatever the price.
Where this information comes from
- Mississippi Department of Revenue: Motor Vehicle E-Lien Program — Supports the release deadline, the penalty and the recertification schedule.
- Mississippi Department of Revenue: Motor Vehicle FAQ — Supports electronic lien transactions, replacement titles, title bonds and the privacy rules on records.
- Mississippi Department of Revenue: Motor Vehicle Titles — Supports the title assignment rules and the warning on blank buyer lines.
- Mississippi Department of Revenue: Motor Vehicle services — Supports the title status link and the e-Services record accounts.
- NMVTIS: consumer information — Supports what a national title report covers and its limits.
Sources and photos: Facts checked against the sources above in November 2026. Photos by Sander Jeurissen, Wesley Tingey and Owen Michael Grech on Unsplash; diagrams by NationalCarReport.
Keep reading
- Vehicle Lien Check by VIN: Nationwide Lien, Theft and Impound RecordsThe same search for a car titled in any state.
- DMV Lien Release Search: How to Confirm a Lien Is GoneHow to tell whether a lender has really let go.
- Buying a Private-Party Car That Has a Lien: Safe StepsWhat to do if the car you want still has a loan on it.
- Electronic Lien and Title (ELT): What a Car Buyer Should KnowHow a title can exist only as a record in a system.
Frequently asked questions
How do I do a Mississippi lien search?
Type the VIN from the car into the preview and read the lien, theft and impound lines. Then ask the seller which lender financed it and request a dated payoff letter. The revenue department records the lien on the title; the lender alone can release it.
Can I search Mississippi liens by license plate or owner name?
Not here. The search runs on the VIN. Federal law, the Driver's Privacy Protection Act, shields names, addresses and licence numbers in motor vehicle records, and the state releases them only to applicants with a qualifying exemption. Get the VIN from the vehicle, its title or its registration instead.
How long does a Mississippi lender have to release a lien?
A lender with a federal employer number has 14 days after payoff to clear the lien online. The revenue department says a $250 penalty may be assessed per late release. Individuals who hold a loan on a car are outside the electronic process, so ask how they plan to release.
Does a clean result mean the car has no lien?
No. A clean preview only means the sources it reads showed no claim. Lender claims are not gathered in one national file, and records can trail a recent loan. Treat a blank as one clue, then ask for the title, the lender's name and written proof of payoff.
What if the seller cannot produce a title?
Hold your money until it is resolved. The state wants a replacement title before a sale proceeds when the original is gone. If the owner cannot supply any title, the buyer's route is a bonded title, which needs a surety bond, an affidavit of ownership and a bill of sale.
Now check the car itself
The guide explains what to look for. The report shows what this VIN has on record.