THE SHORT ANSWER
To check an Iowa car for a lien, enter its VIN in the preview and note any lender it names. Then ask a county treasurer for a certification, which lists each secured party on the date and hour you request it. A named lender means a payoff and written release are needed before you pay the seller.
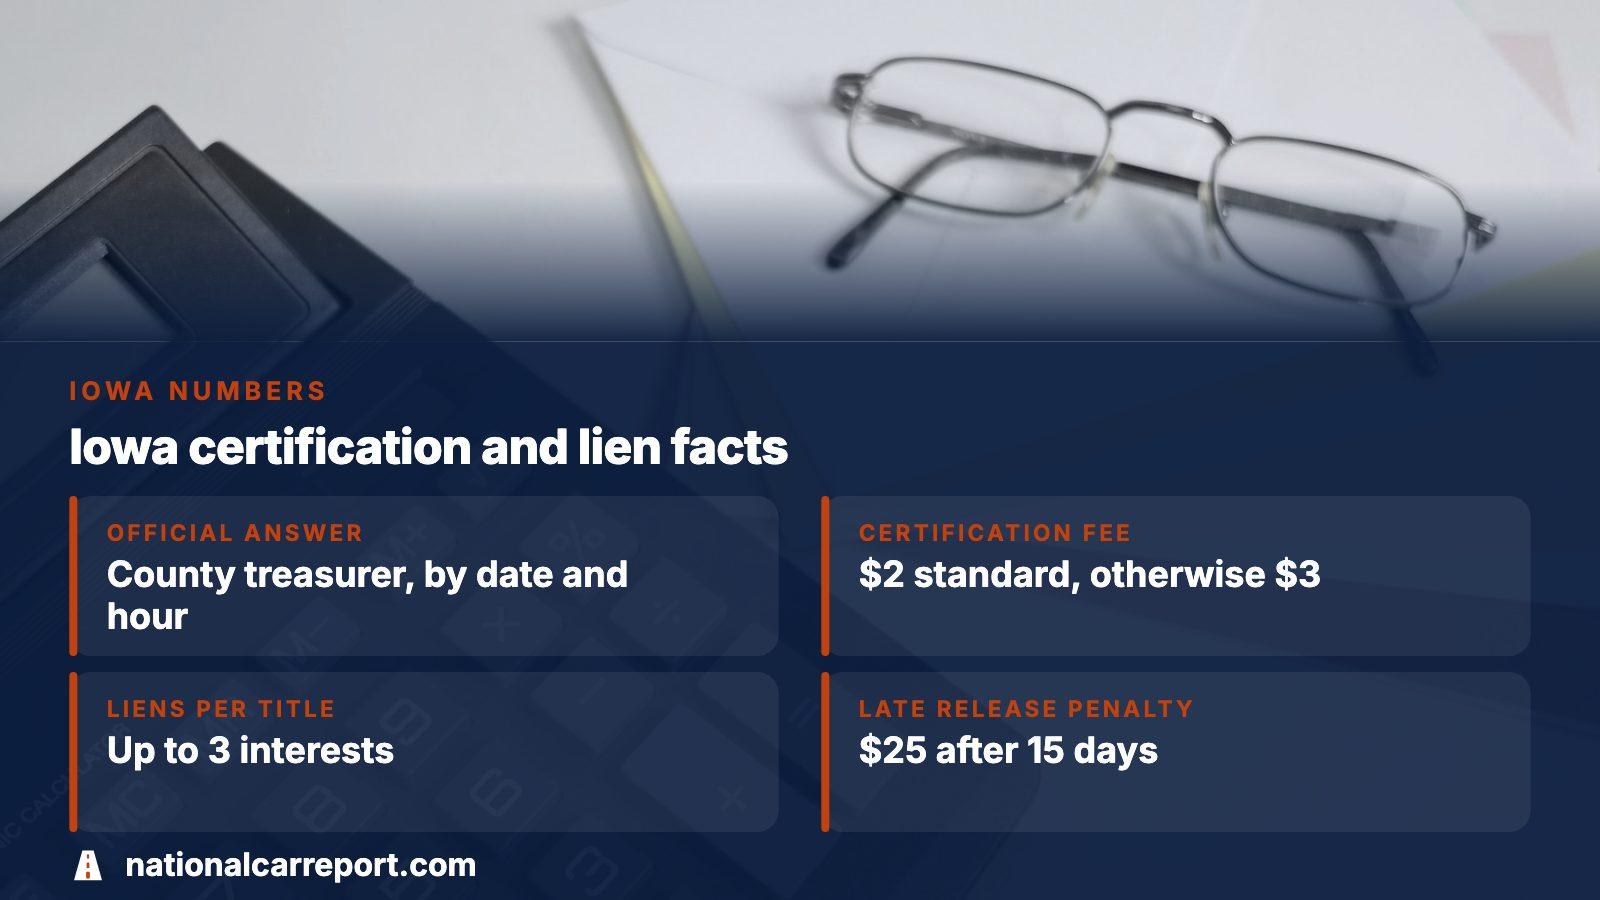
- Official lien answer
- A county treasurer certifies liens by date and hour
- Certification fee
- $2 on the standard form, otherwise $3
- Liens on one title
- Up to 3 security interests
- Lender release penalty
- $25 owed to the payer after 15 days
What an Iowa lien search turns up
Think of a lien as the financing company's hold on a vehicle it paid for. While the balance is open or the hold has not been cleared, the lender keeps a stake in the car no matter who drives it or what the listing says. Our preview reads the VIN and reports claims it can find, along with two other holds that sit on the same number.
- Lender claims: a bank, credit union or finance company named against the car
- Impounds: a record that a tow yard held the car, and how that ended
- Theft: a stolen report that was never closed out
- Title brands such as salvage, which reshape what the car is worth
The preview lookup carries no charge. Add the full report only after a car survives that first screen and a deposit is close; it is purchased separately.
How Iowa records a lender's claim
In Iowa a lender locks in its claim by giving any county treasurer an application that lists the lien, together with a $20 fee for each one. The day that paperwork arrives is the day the claim counts from, even if the title is stamped later. The treasurer then writes the lender and that date on the title and in the county's records.
One Iowa title can show up to 3 liens at once. That matters for a used car that was refinanced or used as collateral for a second loan: a single clean-looking lender line does not prove there is only one.
The practical point
The claim lives in county and state records, not on the car. A seller can be honest, sincerely believe the loan is gone, and still be wrong.
Why there may be no paper title to see
When a lender files its claim electronically, Iowa does not print a title at all until every lien is released. The lender at the top of the list receives a digital copy instead, and for odometer purposes the law treats that lender as holding the title. So a seller with an electronic lien truly cannot give you a title, because none exists on paper.
That is not a red flag in itself. It does change what you should ask for. Rather than a promise that the title is on the way, ask which lender holds the claim, what the payoff is today, and whether that lender will release the car at closing.
After a payoff, if the lender never prints a paper title, Iowa rules let the owner apply to a county treasurer or the state for one to be printed. Any single owner can file that request.
Running the search, step by step
Do this before you drive across the state or leave a deposit. Read the VIN off the car itself, check it against the seller's paperwork, and make sure no letters have been mixed up. A VIN has no letter O or letter I.
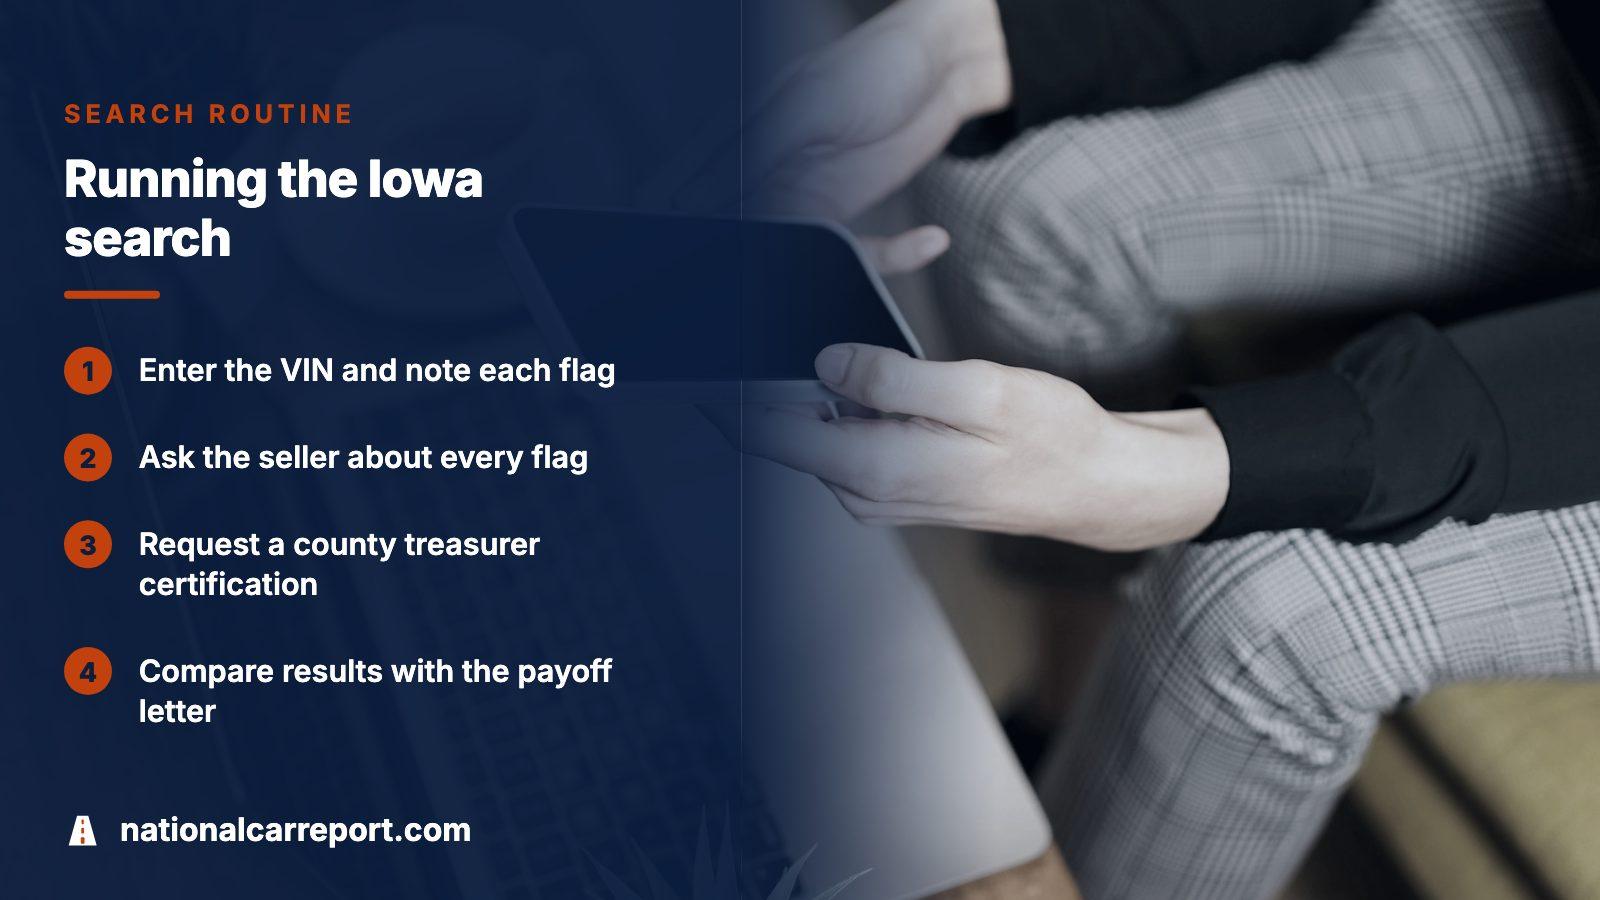
- Enter the VIN in the preview and write down any lender, yard or theft flag.
- Ask the seller about every flag in writing, by text or email.
- Request a certification from a county treasurer for the same VIN.
- Hold both results against the payoff letter the seller gets from the lender.
- Buy the full report once the car is a real contender.
Two matching answers are a good sign. Two different answers are a reason to stop and find out why.
The county treasurer's certification
Iowa gives you a direct route to the official answer. On request from anyone, a county treasurer certifies whether any liens exist against a vehicle on a stated date and hour, and names and addresses every secured party. The fee is $2 when your request is on the form that meets Secretary of State standards, and $3 when it is not. A certified copy of the security interests costs $1 per page.
| Item | What Iowa law sets |
|---|---|
| Lien certification, standard form | $2 |
| Lien certification, any other request | $3 |
| Certified copy of security interests | $1 per page |
| What it lists | Each lien and each secured party's name and address |
Because the answer is tied to an hour, a certification is only as fresh as that hour. If a week passes before closing, ask again.
Reading a hit and a blank
A lender in the results is a lead, not a verdict. The loan may be active, nearly paid, or paid with the release still in the mail. Only the lender can say which.
| What you see | Likely meaning | Your move |
|---|---|---|
| A lender is named | A loan may be open | Get a payoff letter before paying |
| Two lenders | A refinance or second loan | Ask for a payoff from each |
| Nothing shows, price is low | A gap in the records, or a problem elsewhere | Run the full report and inspect the car |
| Lien shown, seller says paid | A release may not be filed | Ask for the lender's release in writing |
A blank result does not guarantee a clean car, since a claim may not have reached every source a search reads. That is why the treasurer's certification and a hands-on inspection belong in the same plan.
Getting a lien released before you pay
When a loan is paid off, the lender records the cancellation on the title, on a notarized letter, or on the state's Form 411168, and sends it to a county treasurer. One form is needed for each vehicle. The treasurer notes the release without a fee.
The safest sale for a car with an open loan is a payoff at closing: your money goes to the lender, and the release comes back to the seller and then to you. If the lender is slow after being paid and asked in writing, Iowa law makes it forfeit $25 to the person who paid if it has not released within 15 days.
Mind the clock
Your time to apply for a new title is 30 days, but if a prior lien still has to be released, that period does not start until the release is on file.
Iowa lien check cost and next steps
Entering a VIN in the preview is free. The report behind it is one payment, never a recurring plan, and the prices are listed on our pricing page. A multi-report pack suits a weekend spent comparing several Iowa cars.
A sensible order is the free preview first, the county certification on your shortlist, then the full report on the car you plan to buy. Hand over money only after the lien question has a written answer and the number stamped on the car agrees with every document.
Where this information comes from
- Iowa Code 321.50: security interest provisions — lien filing, electronic liens, release and the treasurer certification fee
- Iowa Code 321.45: title must be transferred with vehicle — seller's lien statement and the 30-day title window
- Iowa Administrative Code 761 chapter 400 — release form options and printing a title after an electronic lien
- Department of Justice: NMVTIS for consumers — what the national title system shows buyers
Sources and photos: Facts checked against the sources above in November 2026. Photos by Zoshua Colah, Jakub Żerdzicki and Cht Gsml on Unsplash; diagrams by NationalCarReport.
Keep reading
- Vehicle Lien Check by VIN: Nationwide Lien, Theft and Impound RecordsHow a lien check works in any state
- DMV Lien Release Search: How to Confirm a Lien Is GoneConfirming a lender actually released the claim
- Car Lien Holder Search: How to Find the Lender Behind a VINFinding who holds the loan on a car
- Iowa Title Check: Lien, Theft and Impound Tests to Run Before You PayIowa title brands, salvage rules and transfer day
Frequently asked questions
How do I do an Iowa lien search on a car?
Start with the VIN in the free preview, which flags lender claims it can find. Then ask a county treasurer for a lien certification on the same VIN. The treasurer names every secured party as of a stated date and hour, so the answer is official and dated.
Can anyone request an Iowa lien certification?
Yes. Iowa law says a county treasurer certifies liens on a vehicle on request of any person. You do not need to own the car. The fee is $2 on the standard form and $3 on any other request, plus $1 per page if you want a certified copy.
The seller claims the loan is paid, yet a lender still appears. Now what?
Ask for the lender's written release, which may be on the title, a notarized letter, or Form 411168. Paid loans sometimes stay on record until that paperwork reaches a county treasurer. Hold back the purchase price until you hold the release or the lender confirms the payoff in writing.
Why can the seller not give me a title?
If the lender filed electronically, Iowa prints no paper title until all liens are released, so the seller may have nothing to hand over. Ask for the lender's name and payoff figure, and arrange for the lender to be paid from your funds at closing.
Does a clean lien result make the car safe to buy?
No. It tells you about lender claims, not mechanical condition or hidden damage. Pair it with a full report, a check of the VIN on the car against the paperwork, and an independent inspection before you commit any money.
Now check the car itself
The guide explains what to look for. The report shows what this VIN has on record.