THE SHORT ANSWER
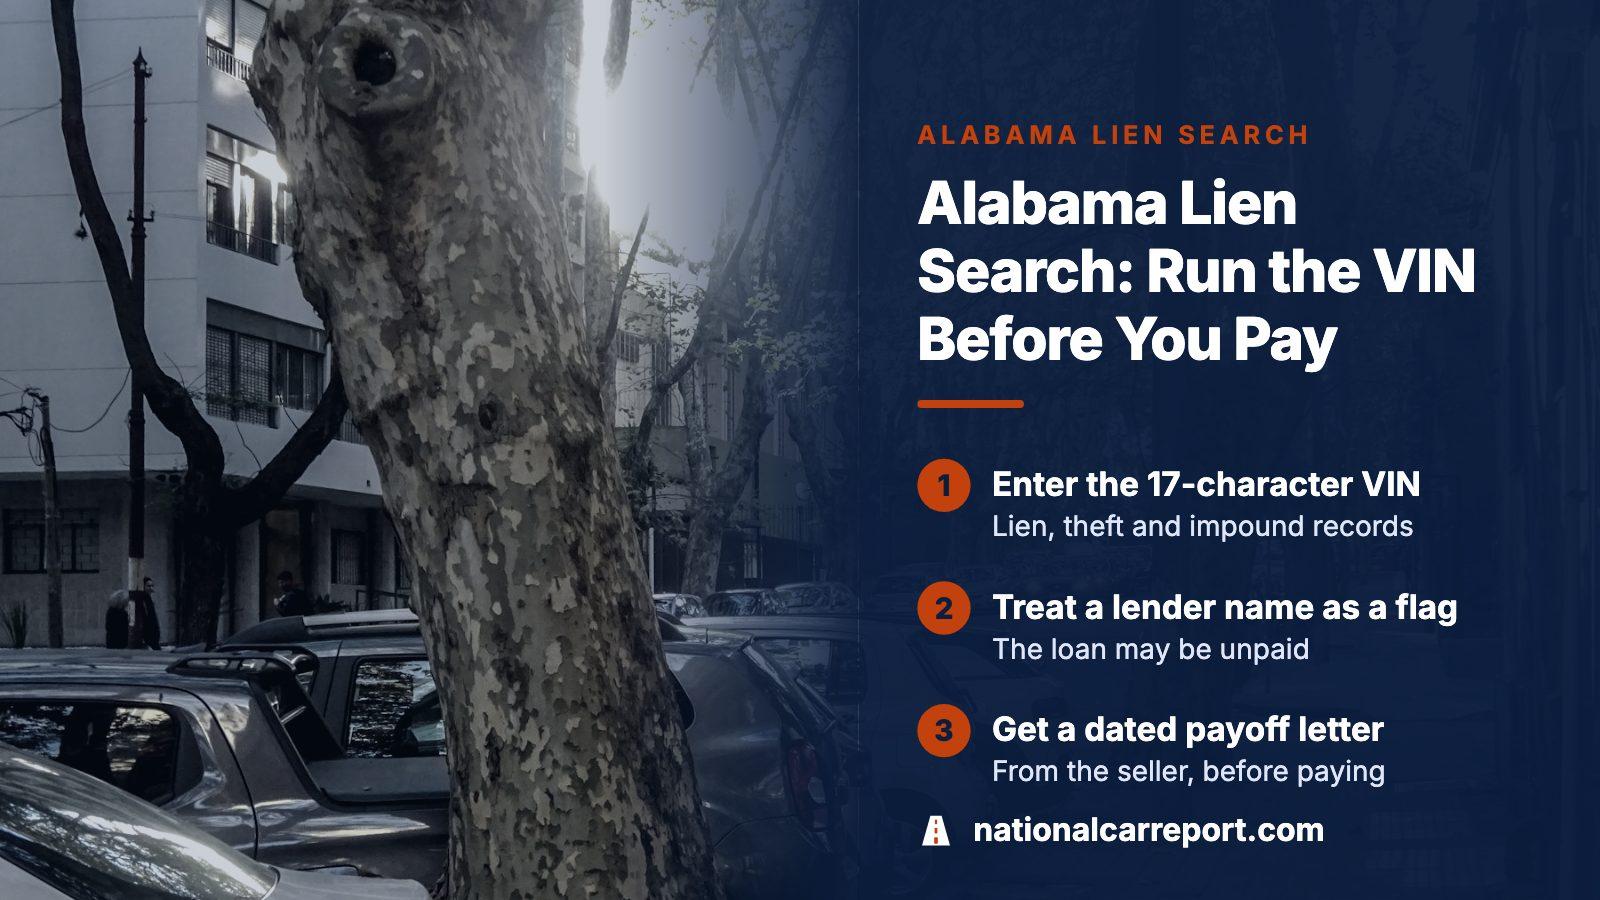
To search for a lien on an Alabama car, take the 17-character VIN off the vehicle and enter it in the preview. The search looks for lien, theft and impound records filed under that number. A named lender suggests the loan may be unpaid. A blank proves nothing, since lender claims are not gathered in one national file. Get the lender's name and a dated payoff letter from the seller before paying anything.
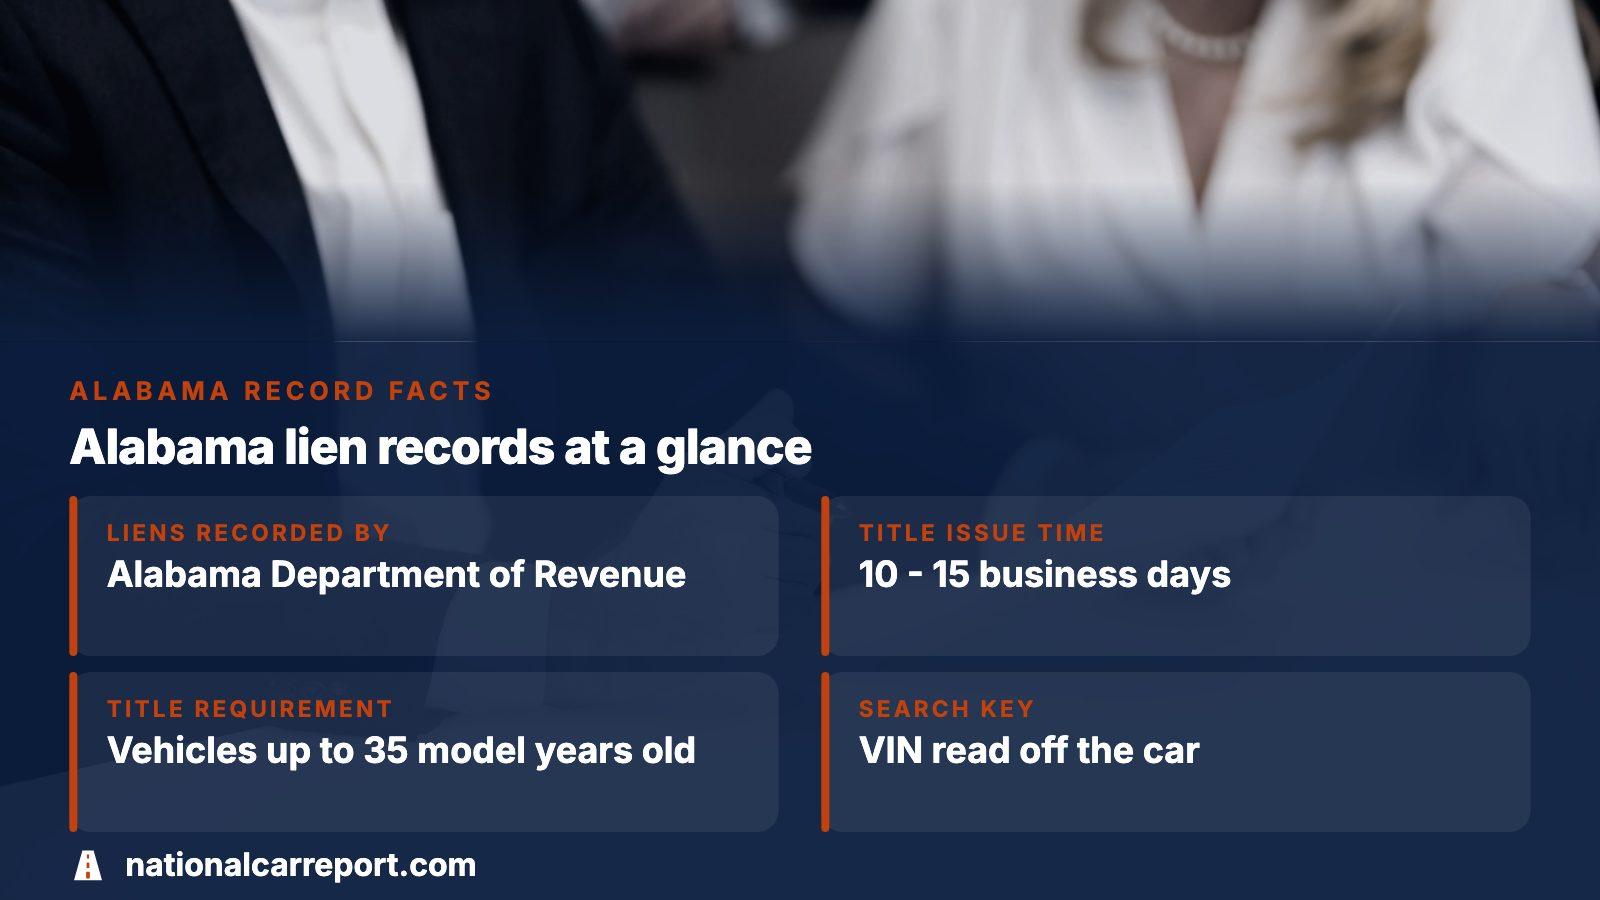
- Search key
- The VIN, read off the car itself
- Who records Alabama liens
- The Alabama Department of Revenue, through its titling system
- Title issue time
- Normally 10 - 15 business days after a correct application
- Alabama title requirement
- Vehicles up to 35 model years old that are domiciled and registered in the state
What an Alabama VIN search can turn up
A seller can be honest and still not know who else has a hand on the car. A lender may have financed it, a tow yard may have held it, and police may have listed it as stolen at some point. Each of those records is attached to the VIN. NationalCarReport's preview gathers what it can find on all three, wherever the car was titled before it reached Alabama.
- Lien records: a lender's claim, if it reached a source the search reads
- Impound records: a note that a yard held the car, and whether it was sold off
- Theft records: a stolen report, and whether the car came home
- Salvage or flood brands, which pull the value down
How Alabama puts a lender's name on a title
Alabama keeps lien data inside the Department of Revenue's titling system. Banks and credit unions based in Alabama, licensed dealers and county license plate officials all act as designated agents that file title applications, and the lender's name on the application has to match the name on the back of the old title exactly. The department says an application that reads Bank Loans NA on one page and Bank Loans on another gets rejected.
The state also issues electronic lien and title records. When a lender's agent is set up for it, the title that records the lien can exist only in the system. So a seller who has no paper title in hand is not automatically hiding anything, but the lender's name and a payoff letter become the only proof you have.
The lender's name is the thing to chase
If the title shows a lender, you are not buying the car from the seller alone. Get the lender's name, call it, and have it confirm in writing what it is owed and how it will release the claim.
Running the search in five steps
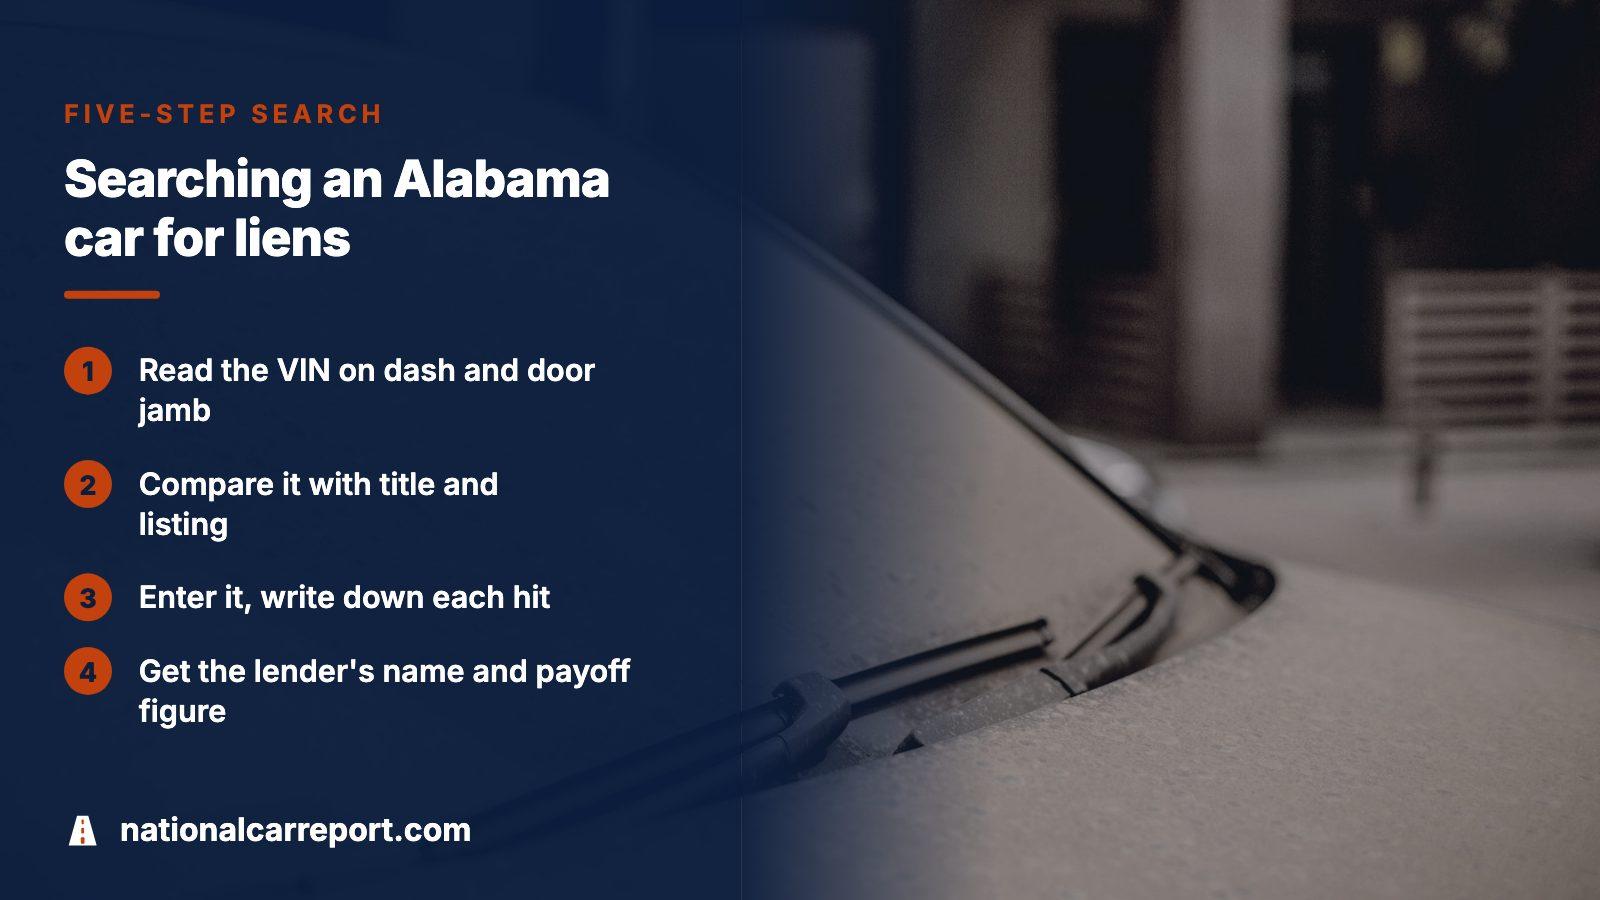
- Read the VIN on the car itself, once on the dashboard plate and once on the door-jamb sticker, and confirm both agree.
- Hold that number up against the title, the sale paperwork and the listing.
- Enter it in the preview and write down each lien, theft or impound hit.
- If a lender shows up, have the seller name it and supply a payoff figure that carries an end date.
- Decide whether to continue to the full report before you hand over a deposit.
The Alabama quirk: cars that arrive on another state's title
When another state's lender is holding the title, Alabama declines to issue its own. The car can still be registered here, provided the registrant is the named owner on that other state's title, the lender is on record there and physically has the document. At the county office the owner presents a copy, or a printout from that state's system.
Some states mail the title to the owner instead of the lender. A car from Kentucky, Maryland, Minnesota, Missouri, New Jersey, New York, Oklahoma, Wisconsin and a few others must be titled in Alabama, with the old title surrendered. For a buyer, the lesson is plain: an Alabama plate does not tell you where the lender's claim was first filed.
| Situation on arrival | What Alabama does |
|---|---|
| Lender holds the out-of-state title | Car can be registered without an Alabama title |
| Title was sent to the owner (listed states) | Owner surrenders it and the car is titled in Alabama |
| Paid-off lien never reported, title lost | Replacement needs a lien release statement |
Reading what the preview shows
| Preview line | Likely meaning | Your move |
|---|---|---|
| A lender is listed | The loan may still be open | Get a payoff letter and the lender's release process |
| Impound record | A yard held the car at some point | Ask who claimed it and what was paid |
| Theft record | The car was reported stolen | Stop and confirm recovery with the seller and police |
| Nothing found | No claim reached the sources searched | Still ask for the title and the lender's name |
Why a blank result still needs a question
The federal title database covers five things: where the car is titled and since when, brands, mileage readings, and the total-loss and salvage records. Lenders are not among them. The system's own site describes a short, clean report as good news, then urges buyers to add a physical inspection.
So a lien can exist without showing in any single database. Treat the preview as a way to find claims early, and treat the seller's paperwork as the way to confirm there are none. A seller who claims the loan is settled should be able to produce the lender's written release, which carries more weight than a promise.
A paid-off car should come with paper
Ask for the release or a title that shows the lien cleared. Alabama says a lender's release that was never reported can surface later, when a lost title needs replacing.
If a lender holds a claim on the car
You have three workable paths. The seller pays the loan off first and hands you a clear title. You and the seller close the sale at the lender's office, so the payoff and the release happen together. Or you walk away. Do not pay the seller and trust that the money will reach the lender, because the lien stays on the car after the sale.
Once the department receives a correct application, a title normally issues in 10 - 15 business days, and the mailed paper adds another 3-5. The department does not offer same-day printing. A seller promising a clean title by tomorrow is promising something the state does not do.
- Payoff letter with an expiry date and per-day interest
- The lender's address and the release method it uses
- A written note of the VIN on every document
When the seller has no title and no lender
Sometimes the file is simply incomplete, for example after a dealer closes before filing the paperwork. Alabama can require a cash or surety bond when it is not satisfied about ownership or about undisclosed security interests. After approval, the applicant has 90 days from the bond's execution to apply through a designated agent. That is the seller's job to finish before a sale.
A buyer who cannot get a title that matches the VIN, the seller's name and the lender's release should treat the deal as unsafe until they can. Alabama also does not require a notary on a title assignment, so a signature alone proves little. Check the names against the seller's identification.
What the search costs and where to go next
The preview is free and takes the VIN only. If it shows a lien, theft or impound line, or if you are close to paying, the full report adds the detail behind those records in one payment, and no subscription. The pricing page lists current rates. Pair the report with a mechanic's inspection, since neither tells you the condition of the brakes.
For the title itself, the Department of Revenue's online services let owners and lenders manage a lien, check an application's status and request certified title records. As a buyer, ask the seller to use them and hold on to each receipt.
Where this information comes from
- Alabama Department of Revenue: Motor Vehicle — Supports the online lien, title status and records services.
- Alabama Department of Revenue: lien FAQs — Supports the out-of-state title rules and the lien release statement.
- Alabama Department of Revenue: title application FAQs — Supports designated agents, the lender name match and the notary point.
- Alabama Department of Revenue: general title FAQs — Supports electronic titles, processing times and which vehicles need a title.
- Alabama Department of Revenue: surety bond FAQs — Supports the bond route when ownership is in doubt.
- NMVTIS: understanding a vehicle history report — Supports the five items a national title report covers.
Sources and photos: Facts checked against the sources above in November 2026. Photos by Nikolai Kolosov, JavyGo and Carrie Allen www.carrieallen.com on Unsplash; diagrams by NationalCarReport.
Keep reading
- Vehicle Lien Check by VIN: Nationwide Lien, Theft and Impound RecordsThe same search for a car from any state.
- DMV Lien Release Search: How to Confirm a Lien Is GoneHow to tell whether a lender has truly let go.
- Car Lien Holder Search: How to Find the Lender Behind a VINFinding which lender holds the claim so you know whom to call.
- Electronic Lien and Title (ELT): What a Car Buyer Should KnowHow a title can exist only as a record in the system.
Frequently asked questions
How do I do an Alabama lien search?
Type the VIN, read from the car, into the preview and look at its lien, theft and impound lines. Then ask the seller which lender financed it. The Department of Revenue records Alabama liens, and only the lender can release one, so a written release is the final proof.
Can I look up an Alabama car lien without the owner's name?
Yes, the VIN is enough for the preview. Liens are tied to the vehicle, so the owner's name is not needed. Nothing here returns private details about people. For the official title file, the department takes certified record requests through its portal.
Does a clean search mean the car has no lien?
No. The federal title system follows title state, brands, mileage, total loss and salvage, but not lenders. A blank means no claim was found in what was searched. Confirm with the seller's title, a lender release and, if you can, a call to the lender.
What if the car came from another state?
Alabama may register it without writing a title of its own when the other state's lender holds the paper. Cars from states that mail titles to owners are titled in Alabama. Either way, the lender's claim may have been filed elsewhere, so a VIN search matters more.
How long does a new Alabama title take?
The usual wait is 10 - 15 business days from a correct application, plus 3-5 for delivery. It offers no same-day printing. If a seller promises a clean title overnight, ask for the lender's release and the application status instead.
Now check the car itself
The guide explains what to look for. The report shows what this VIN has on record.